Read The Evidence · PDF Example
Current Condition Report
An actual commercial inspection excerpt: photographs, observed conditions, and the next qualified review. Customer names and exact property addresses are removed from the public example.
Read The Evidence · PDF Example
An actual commercial inspection excerpt: photographs, observed conditions, and the next qualified review. Customer names and exact property addresses are removed from the public example.
A dated photographic record of the inspected roofing system, supported by observations, property history and clearly stated limits.
Two Property Types. Distinct Case Studies.
Commercial / Industrial
The City of Holden metal-roof project and a redacted commercial condition report show two different situations: a construction scope and an existing-condition investigation.
Commercial / Industrial ↗Specialty / Historic
Follow the State Farm Case Study, explore Euroshield Synthetic Slate, and examine the Ludowici Clay Tile Certificate.
Specialty / Historic ↗A Current Condition Report records what was observable on a specific date. Use it to discuss maintenance, a future project or questions about the property.
Photographs and written findings from the areas included in the agreed inspection.
Relevant history, supporting records and uncertainties that need further investigation.
Consider monitoring, maintenance, repair, additional testing or planned replacement.
When solar is installed, the review can consider visible roof interfaces and penetrations within the agreed scope. System performance and electrical diagnostics are separate services.
Explore existing-solar diagnosticsAnswer every question to see an educational documentation score.
A quick look at the questions, evidence and limits you can expect.
Genuine template excerpt · Not findings for your property
This document records observable conditions. It does not determine insurance coverage or guarantee a claim outcome.
Source: Crown Roof + Solar Investigative Field Report, Clinton field packet. Customer names, addresses and example results are omitted.
These are examples of fields in Crown’s actual packet. A completed report depends on the agreed inspection, accessible areas and reviewed evidence.
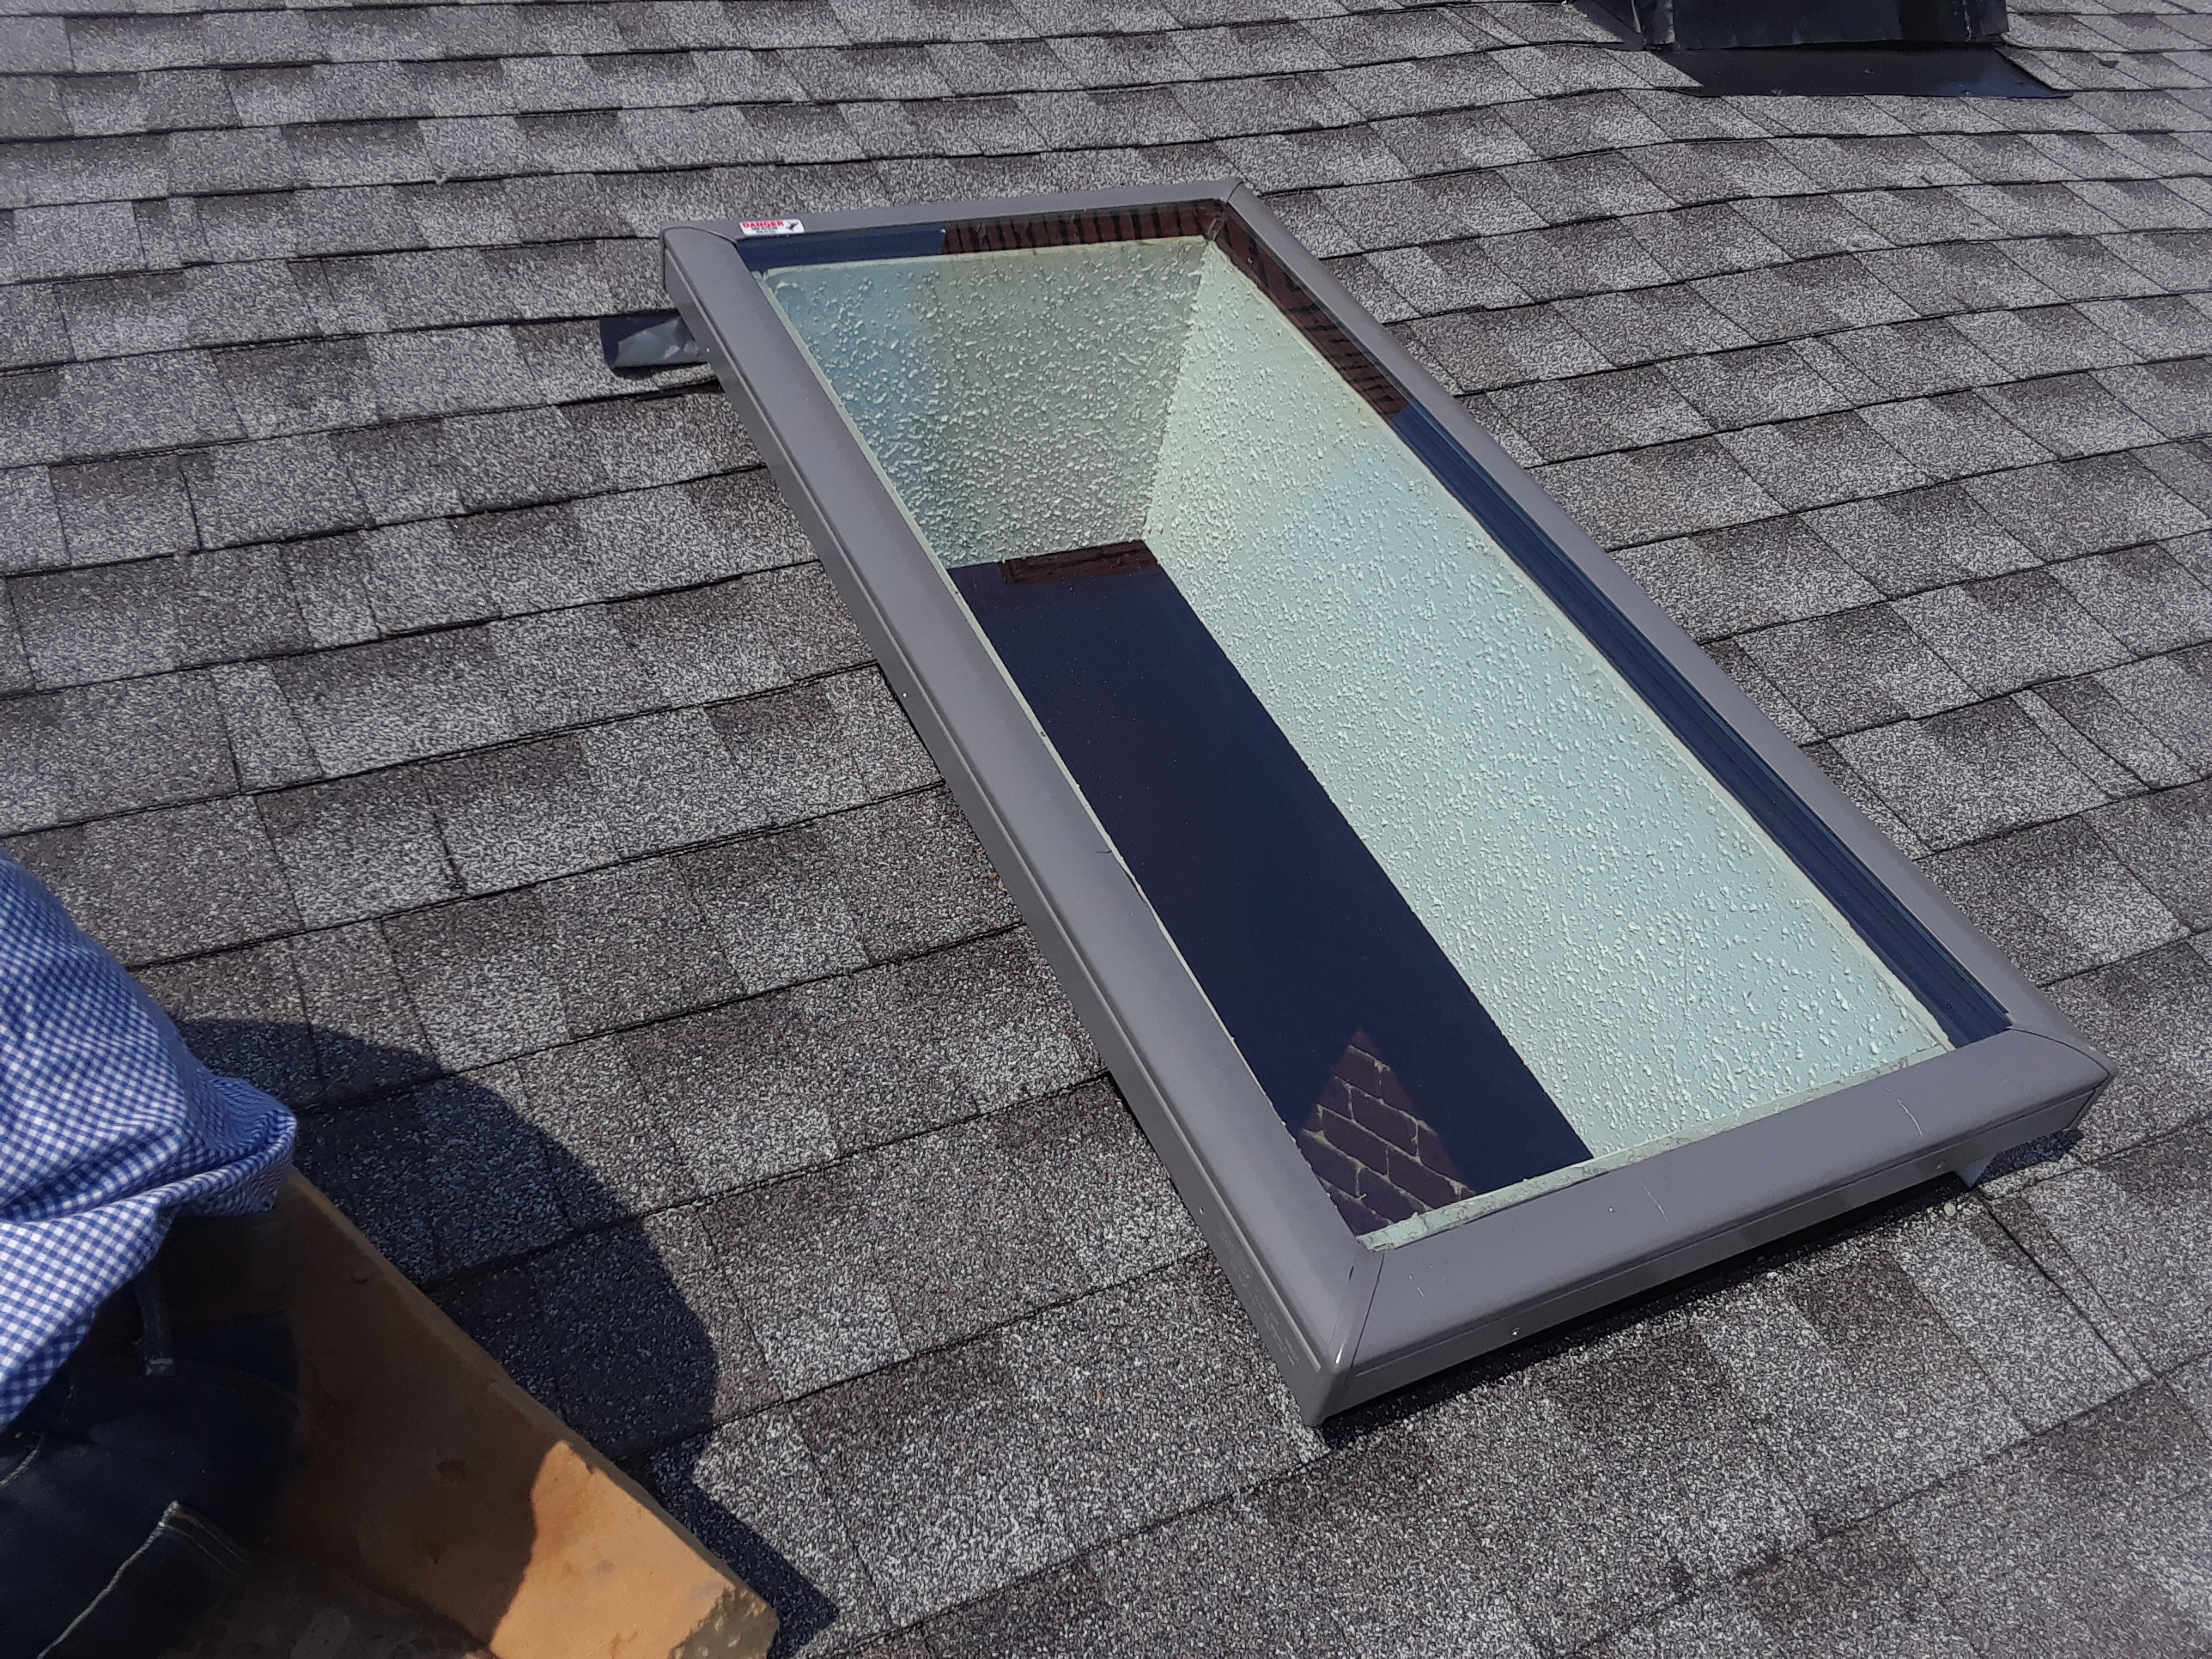
A useful roof review connects observations to the question you need answered. Shingles, skylights and other roof openings each deserve a closer look within the agreed scope.
Your report explains what was observed, what could not be verified and which follow-up is appropriate.
Explore the Kansas City residential review, Kansas City solar controls and Commercial Property methodology.
Current condition / Commercial Property · Clinton, Missouri
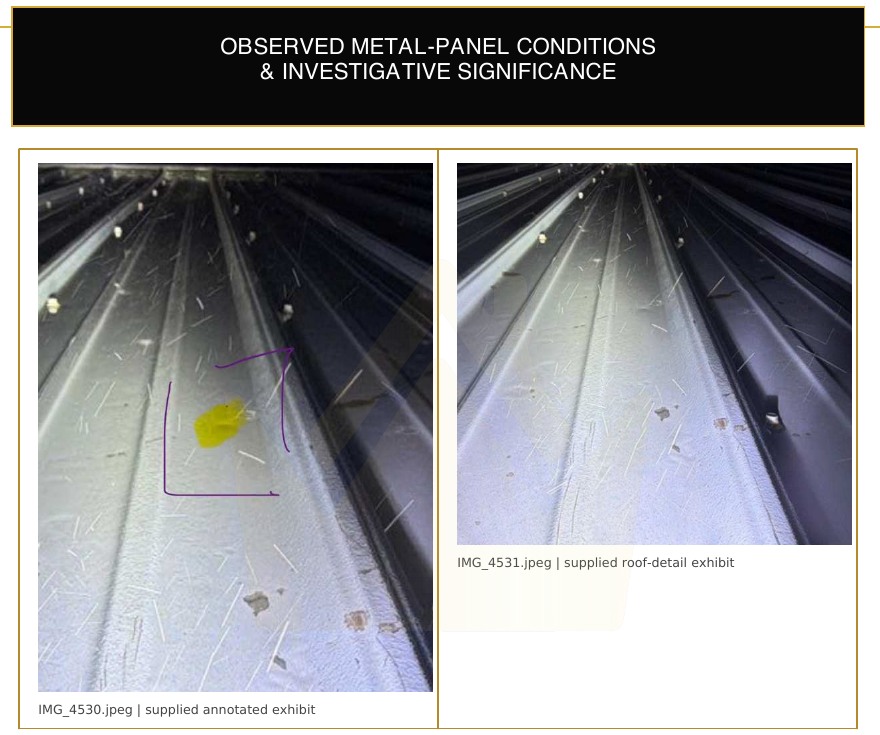
A real Crown condition-report example: record the visible metal-roof condition, preserve the source photographs and identify the investigation still needed.
 Open full image ↗
The report places an annotated view beside a wider view of the metal panel. The original image IDs connect the findings back to the record.
Surface marks, coating condition and fastener observations direct the next inspection. A photograph alone does not establish when or why a condition developed.
The broader Commercial Property record identifies structural concerns for a Missouri-licensed structural engineer. Contractor observations remain distinct from an engineering conclusion.
Three questions / three real examples
Kansas City Residential
Event chronology, physical evidence and unresolved questions.
Commercial Property · Clinton
Photographs, observed conditions and priorities for further review.
Kansas City + Wichita examples
Field markings, material access and documented repair tests.
Roof decisions come with questions about cost, coverage and what happens next. Start here.
Talk through your propertyApproval depends on the cause and extent of damage and your policy’s coverage, exclusions and roof settlement terms. A storm nearby does not automatically qualify a roof for replacement. Ordinary wear and tear is generally excluded.
Crown can document visible conditions, photographs, measurements and the construction work recommended. Your insurer decides coverage and payment. Report a suspected loss promptly and ask your insurer about the deadlines and responsibilities in your policy.
See what a condition report includesThere is no single answer for every homeowner. Rates and renewal decisions depend on the insurer, loss history and applicable state rules, including any storm-related protections.
Ask your insurance agent or company how a claim may affect your policy. Your state insurance department can explain consumer protections or review a complaint. Crown cannot promise that a claim will have no effect on your premium or renewal.
Nearby homes can have different damage, roof conditions and insurance coverage. A neighbor’s replacement does not determine the outcome for your roof.
Ask your insurer for its written explanation. Crown can provide dated photographs and construction findings for you to compare with the stated repair scope. A review may identify questions that need clarification; it does not guarantee a different claim decision.
Explore roof repairabilityA useful price starts with your roof’s size, pitch, materials and access, then accounts for decking, flashing, ventilation, removal and installation. Crown confirms the scope and price in a written proposal.
For an insurance-funded project, your deductible may be only part of your expense. Noncovered work, upgrades and depreciation that your policy does not reimburse can add to your cost. Ask about current payment or financing options; availability, approval and terms must be confirmed in writing.
Request a roof estimatePlan to pay the deductible required by your policy. Do not rely on a promise to hide it in an inflated invoice or misstate the amount paid. Project invoices and payment records should accurately reflect the work and actual charges.
If the upfront cost is a concern, ask Crown about current payment options and confirm any financing terms before committing. Financing can spread payments over time; it does not remove your deductible obligation.
Discuss payment optionsCoverage decisions belong to your insurer. For independent guidance, see the NAIC guide to coverage and out-of-pocket costs or find your state insurance department.
Crown confirms service availability, the inspection scope, any fee and scheduling before the work begins.
This request does not confirm an appointment or purchase.
Tell Crown about your property and choose an email reply or personal phone call.
Continue my requestPrefer to talk? Call 660-333-7386 or email Crown.
Text Crown about this property ↗
Copy a ready-to-use message or open your messaging app. For urgent scheduling, please call.
See what to preserve, how Crown connects the evidence and why a dated baseline matters before your next roof decision.
Explore Evidence IntakeSee the 15-year-old roof example: a $5,000 deductible can leave the owner funding $5,000 under qualifying RCV terms or $15,000 under the illustrative ACV calculation.
See The Calculation & Insurer Sources ↗A dated property record is valuable whether or not storm damage is found.
Explore Figure home equity through Improvifi, or compare personal-loan offers.
Your Questions. Time With Crown.
Talk through your roof, report findings, repair questions or proposal. Choose a video meeting or an in-person review.
 Explore Project Protection ↗Eligible, registered projects. Written terms apply.
Send your property or report request before the meeting so Crown can prepare. Check the calendar’s time zone. Crown confirms the location for in-person reviews. Booking a review does not schedule inspection or installation work. Privacy